Coreware merchant processing
3% flat. Pass it through.
Get a flat 3% processing rate plus a compliant surcharge program that passes the cost of credit card acceptance to customers where permitted. Offset your processing fees instead of absorbing them.
Credit cards only
Disclosed at entry & on the receipt
Coreware handles the compliance setup
Coreware merchant processing
3% flat.
Surcharge
Up to 3% of credit card sales is passed through to the customer.
Disclosure
Shown at the point of entry, at checkout, and on every receipt.
Setup
Coreware handles the compliance setup, in states where surcharging is permitted.
How it works
Three steps. One flat rate.
The surcharge is added to credit card transactions, disclosed up front and itemized on the receipt, so your processing cost is passed through instead of coming out of your margin.
We set you up at 3% flat
Coreware configures your merchant account, terminals and checkout for the surcharge program, and handles the compliance setup for your state.
Credit · 3% surcharge
Debit
Prepaid
Customers see it before they pay
Clear notice at the point of entry and at checkout tells customers a surcharge applies to credit cards before they choose how to pay.
How it works
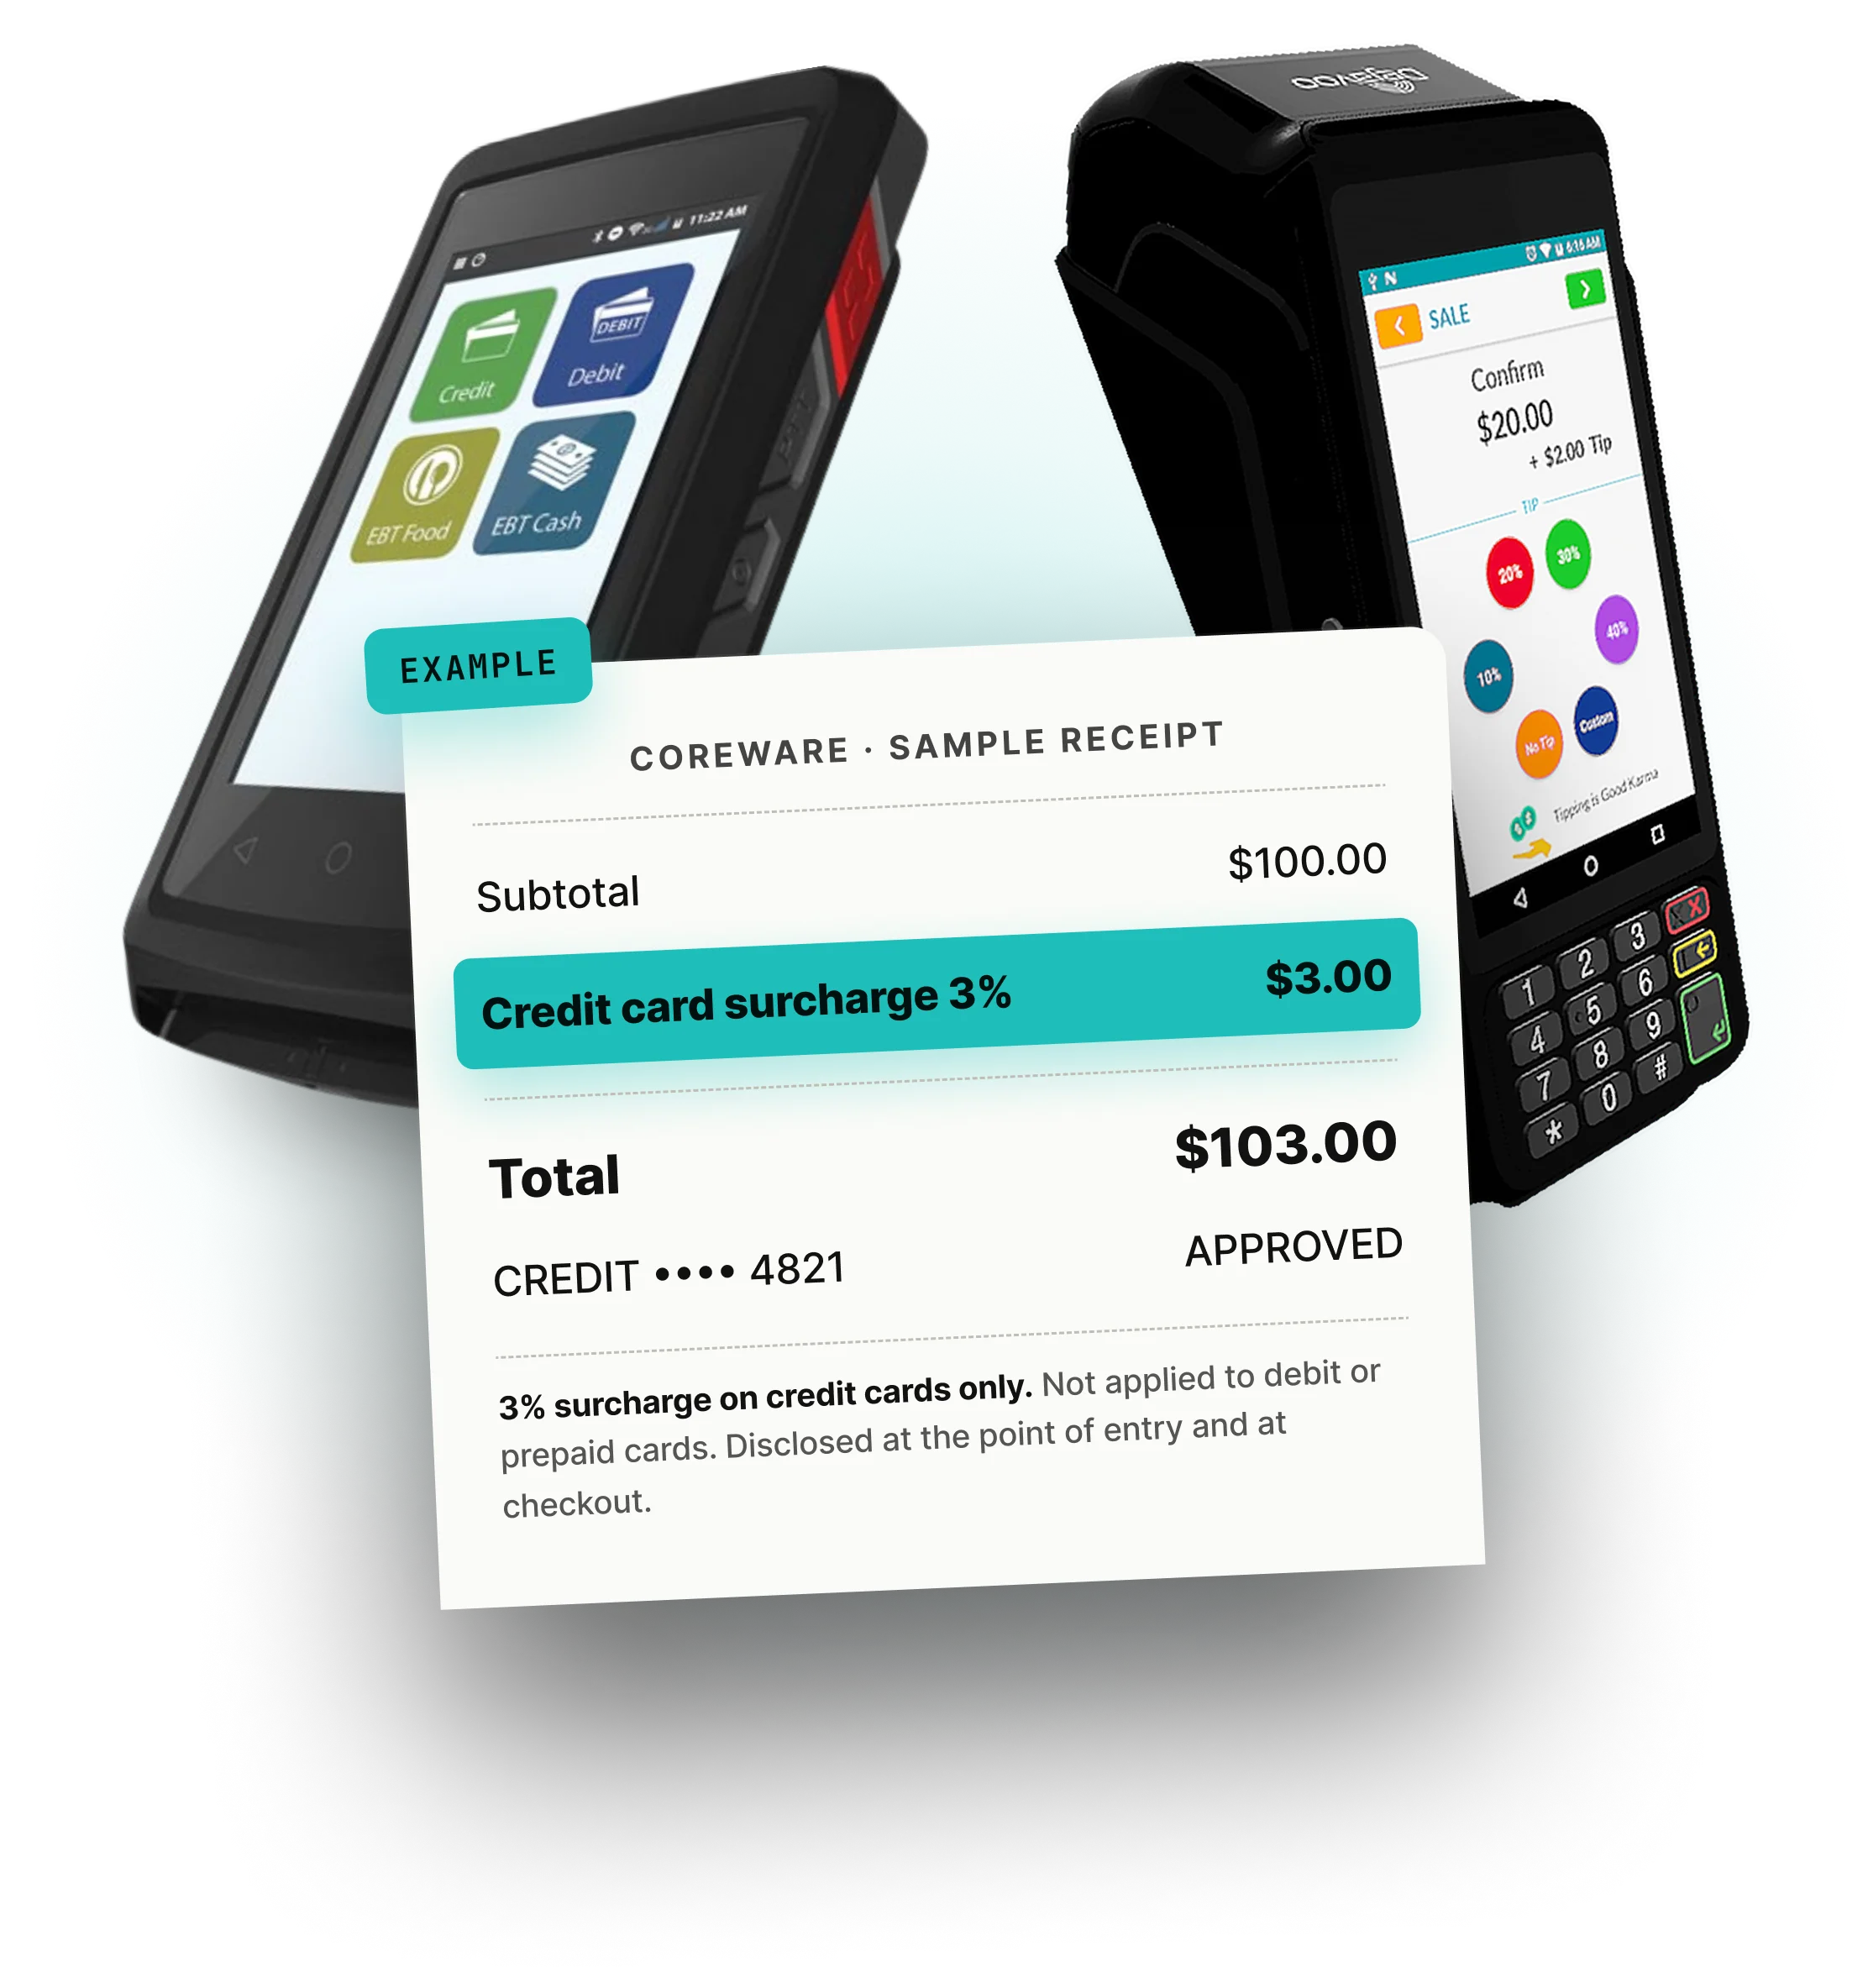
We add a 3% surcharge to credit card transactions. The surcharge does not exceed our acceptance costs. We do not surcharge debit or prepaid cards.
It’s itemized on every receipt
The surcharge prints as its own line, so customers see exactly what was added and you keep a clean record.
Savings example
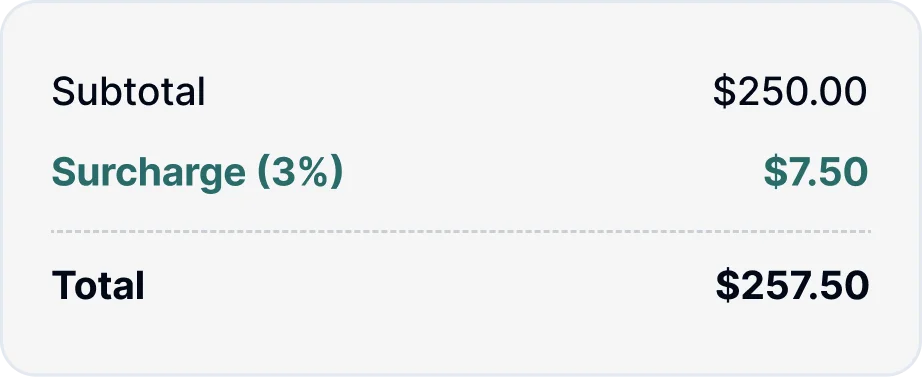
What 3% looks like at your volume.
On credit card sales, the surcharge offsets the processing fee rather than leaving you to absorb it.
$1,500/mo
in fees offset in this example
$18,000/yr
in fees offset in this example
Illustrative example only, not a guarantee of results. Assumes all $50,000 is credit card volume surcharged at 3% in a state where surcharging is permitted. Debit, prepaid and cash sales aren’t surcharged. Because the 3% rate also applies to the surcharge itself, a small difference remains (about 9¢ per $100 of sales). Your results depend on your card mix.
Compliance built in
Surcharging, done by the rules.
Card-brand rules and state laws decide how surcharging works. Coreware builds those rules into your setup so the program holds up.
Credit cards only
Surcharges apply to credit card transactions only. Debit and prepaid cards can’t be surcharged, even when they’re run as credit.
Capped at 3%
Card-brand rules cap a credit card surcharge (Visa’s cap is 3%) and limit it to your cost of acceptance. With a 3% flat rate, the surcharge matches your rate and stays within the cap.
Disclosed at the point of entry
Customers are told about the surcharge before they pay: at the entrance or point of entry, at the point of sale, and before checkout online.
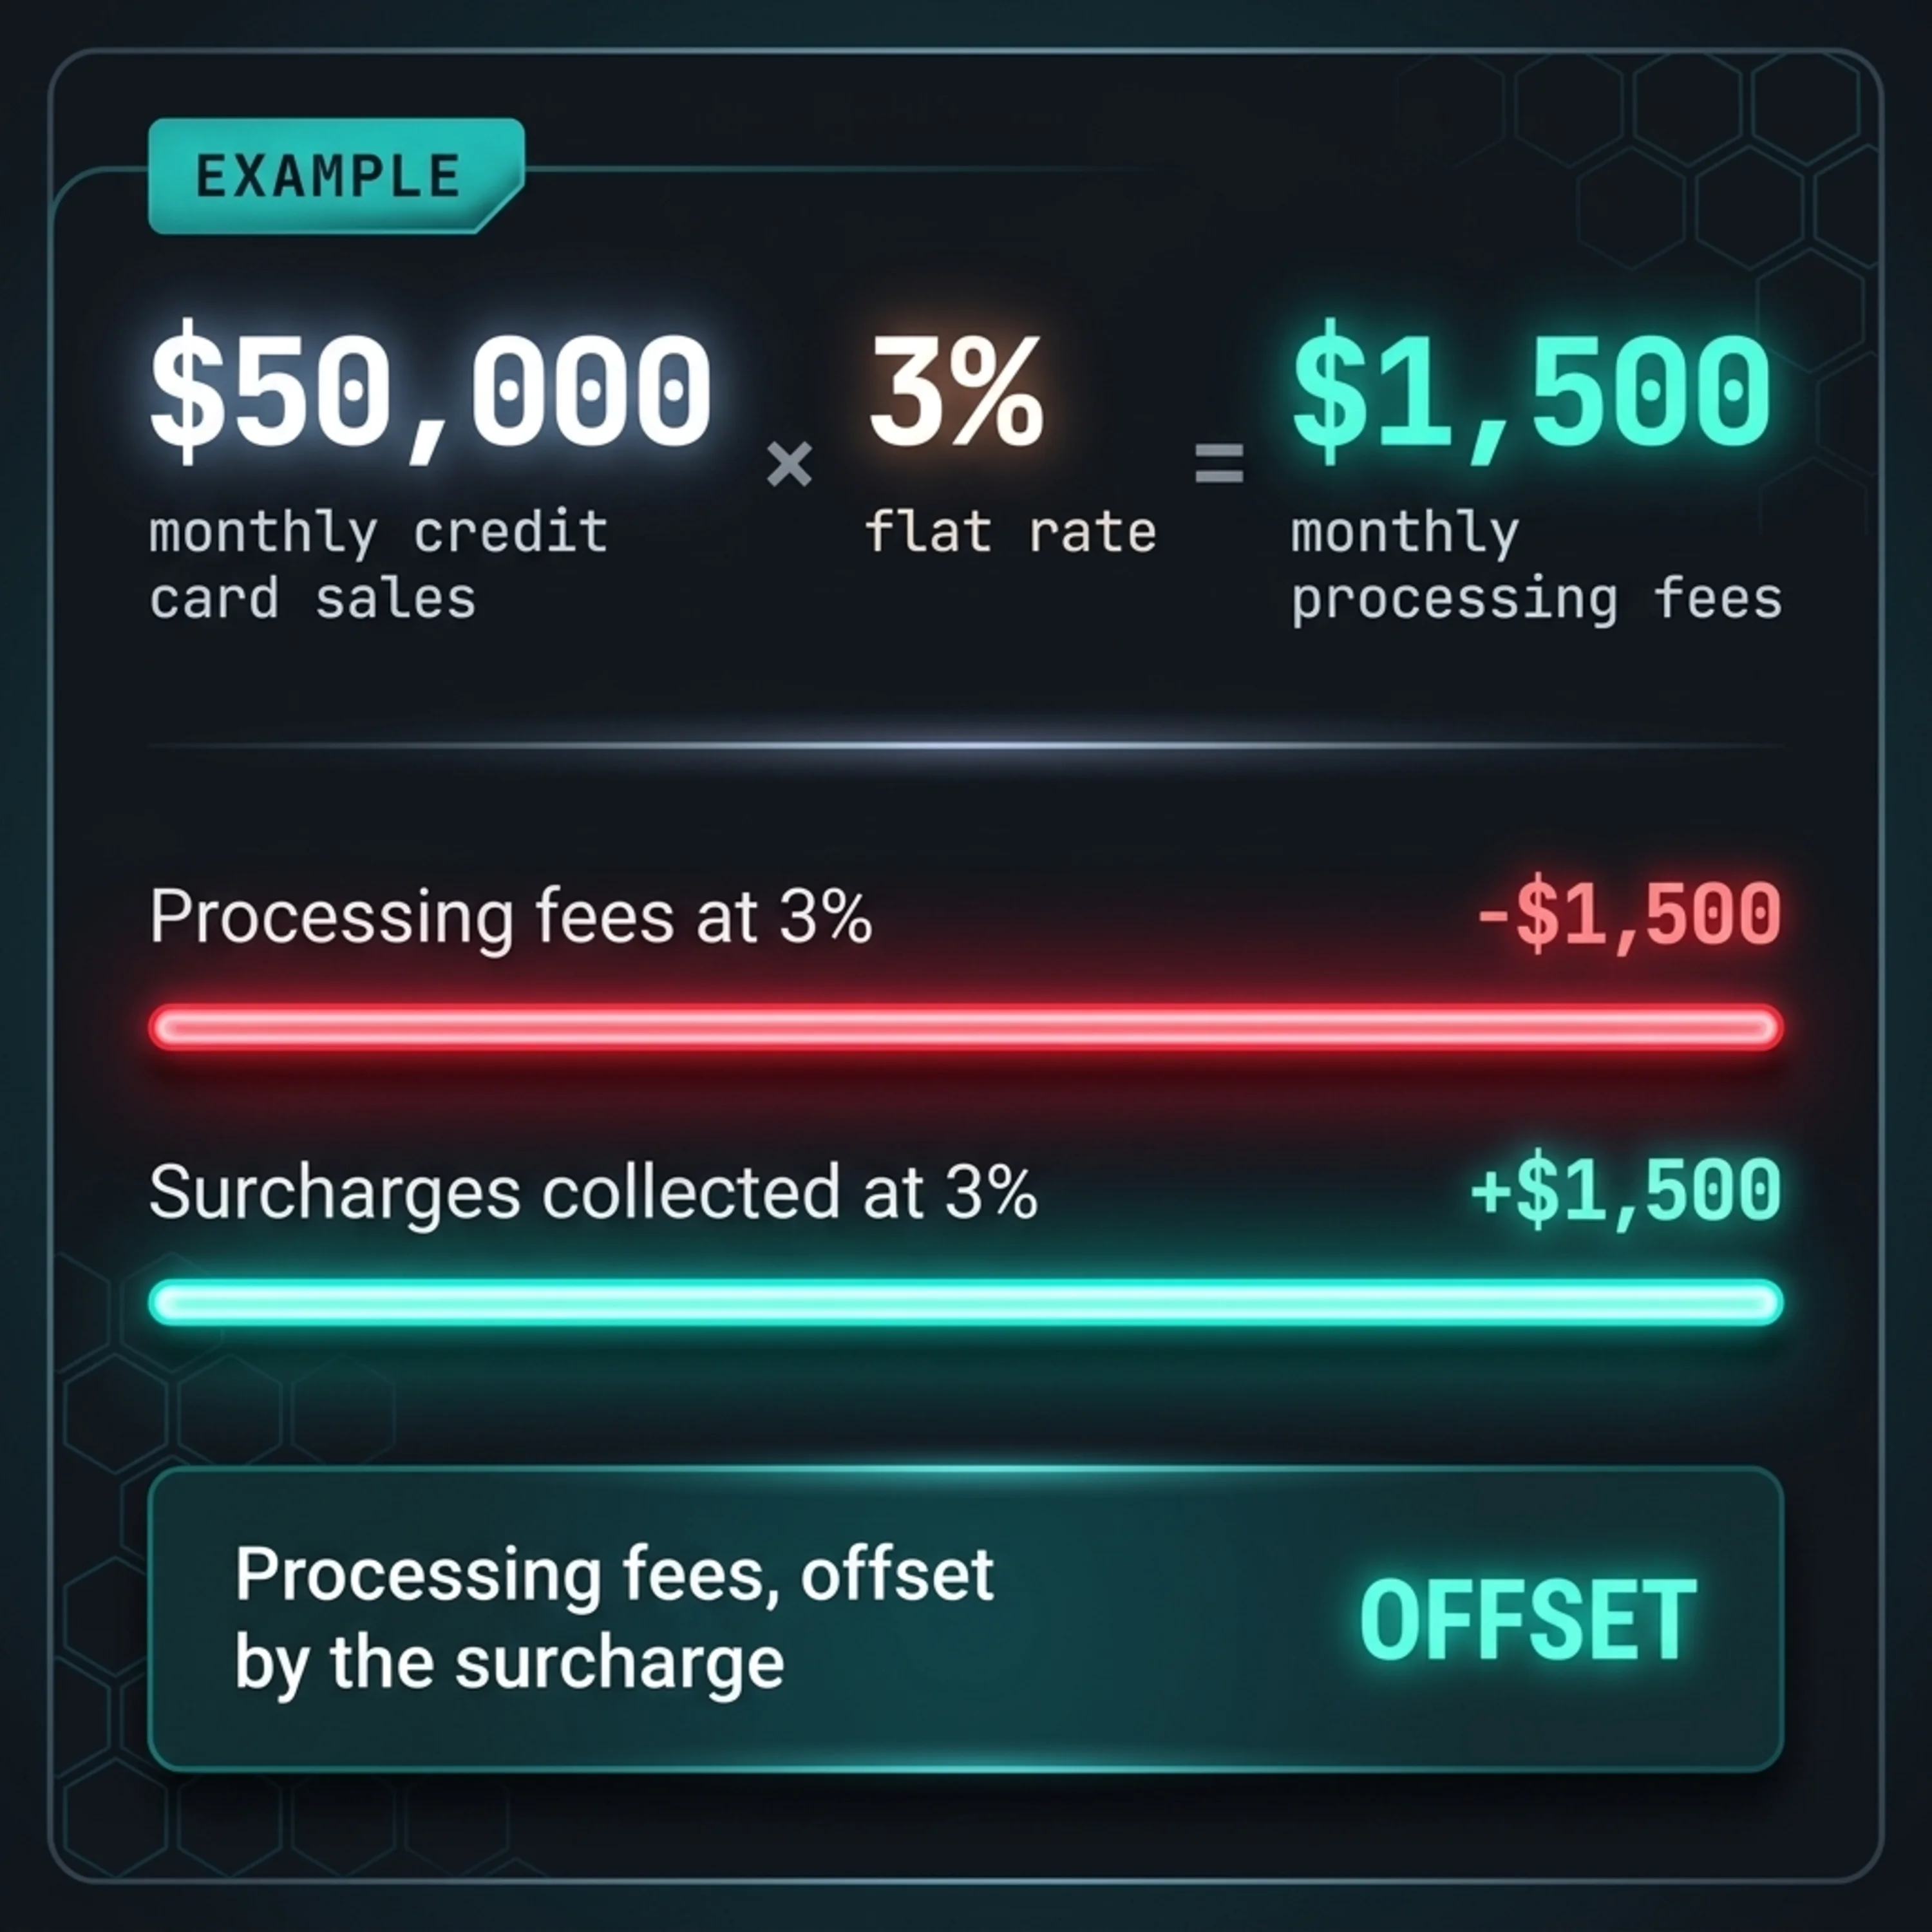
Itemized on the receipt
The surcharge amount appears as its own line on every receipt, separate from the sale.
State rules handled
A few states restrict surcharging. Coreware handles the compliance setup, and surcharging is offered in states where it’s permitted.
Online and phone orders
For card-not-present sales, the surcharge must be disclosed before the customer completes payment and shown on the receipt. Talk to us about surcharging on each of your sales channels.
Debit and prepaid cards
Debit and prepaid cards can’t be surcharged. For those, ask us about cash-discount or dual pricing, where a card price and a lower cash price are both posted up front.
This page is general information, not legal advice. Surcharging is subject to card-brand rules and state law, which can change.
What’s included
Everything Coreware processing already does.
The surcharge program runs on Coreware merchant processing: secure, versatile and built into the Coreware platform.
All card types and brands
Accept every card type and brand in retail, eCommerce, invoicing, mobile and phone orders.
EMV chip to mobile wallets
From EMV chip to mobile wallets, Coreware keeps transactions secure and reliable.
PCI compliant technology
Bank-level security measures safeguard payment information and protect customer and business data.
Next-day funding
Next-day funding helps streamline your finances and improve cash flow.
Built into Coreware
Manage operations and accept payments from a single platform, with simpler reporting and reconciliation.
Dedicated customer support
Coreware’s support team helps with hardware, software and monthly statement questions.
FAQ
Questions, answered.
Don’t see yours? Email sales@coreware.com
Talk to sales
Ready to pass it through?
Tell us about your business and card volume. We’ll walk through the 3% flat rate and the compliance setup for your state.
sales@coreware.com